Navigating a Life Change
Sell first or buy first when moving for retirement?
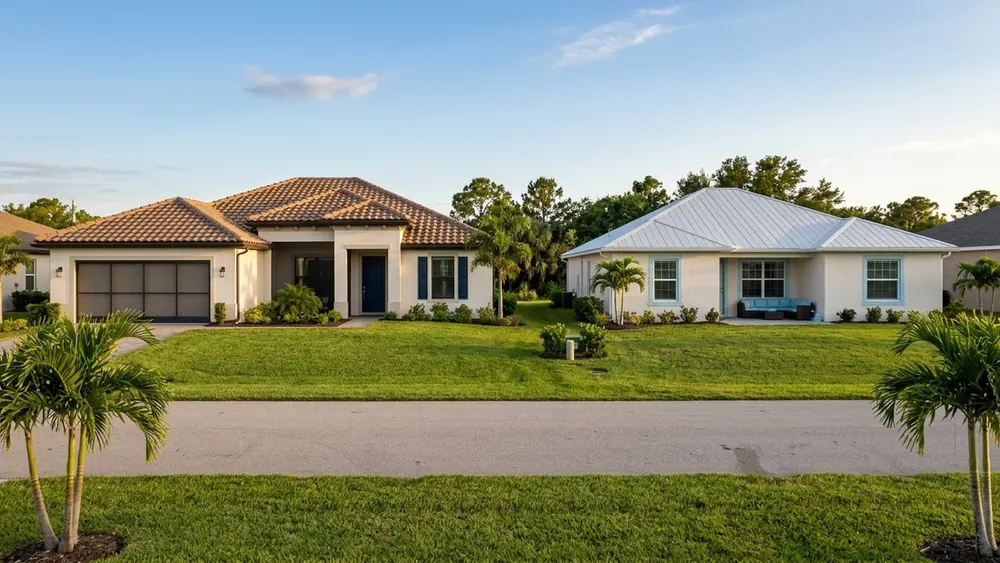
When moving for retirement, sell first if you need the money from your current home to buy the next one, and buy first only if you can comfortably carry two homes for a while. Either way, plan where you will stay if dates differ.
On this page
The direct answer for a retirement move
For most retirement moves, the question of whether to sell first or buy first comes down to one thing: do you need the money from your current home to buy the next one? If you do, selling first is usually the clearer path. If you can comfortably carry two homes for a while, buying first is possible. Either way, a written timeline and a plan for where you will stay if the dates do not line up will save you a lot of worry.
That answer sounds simple, and in a sense it is. What makes it feel hard is that the decision touches money, emotions and logistics all at once. You may love your current home and feel unsure about letting it go before the next one is chosen. Or you may worry about paying for two homes at the same time. Both feelings are normal. The goal is to look at each option calmly and choose the one that fits your situation.
This article works through the choice the way a teacher would work through a lesson. First, what each option really means. Then, the questions that decide it, who answers each one, and the surprises to plan for. If you are planning a retirement move to Punta Gorda, or within it, you can use these steps as a checklist. You do not need to have every answer today. You only need to know which question comes next.
What selling first really means
Selling first means you list and close on your current home before you buy the next one. The biggest benefit is clarity. You know what your sale brought in, so you know what you can comfortably spend. You also avoid the cost and stress of owning two homes at the same time. For many retirees who need the money from the sale to fund the purchase, this order removes the biggest unknown from the plan.
The tradeoff is that you may need somewhere to live between homes. That could mean a short term rental, staying with family or arranging a later move out date as part of your sale. Your belongings may need storage for a while. None of these are unusual, but they do need planning. If you choose to sell first, decide early how you would handle the gap so it never catches you off guard.
Selling first also changes how your home search feels. Because the money question is settled, you can look at homes in Punta Gorda with a clear budget in mind. You are not guessing about what your current home might bring. Some people find this makes the search calmer, because each home is measured against real numbers rather than hopes. Others find the pressure of a temporary living arrangement pushes them to decide faster than they would like.
What buying first really means
Buying first means you find and purchase your next home before your current one sells. The main benefit is that you move once, directly into the new home, with no gap in between. You can take your time settling in, then prepare and sell the old home without living in it. For people who dread the idea of a temporary stay, this can feel like the more comfortable path, at least on paper.
The tradeoff is cost and risk. For a while, you may be paying for two homes, including insurance, utilities and upkeep. If your current home takes longer to sell than you expected, that period can stretch out. Buying first generally suits people who can comfortably carry both homes without needing the sale money right away. Only a licensed lender can tell you what financing options might fit your situation, so that conversation should come early.
There is also a planning question here. If you buy first, you will be managing a sale from your new home, which may mean coordinating showings, repairs and paperwork from a distance. That is very doable with good organization, but it is worth deciding in advance who will check on the old home, how keys will be handled and how you will stay informed. Writing these details down now keeps them from becoming surprises later.
The questions that decide your order
Rather than choosing based on a feeling, it helps to answer a few specific questions in writing. Each one points you toward one order or the other. Some of them you can answer at your kitchen table. Others belong with a lender, a tax advisor or an estate or elder law attorney. Linda can help you sort which question goes to which person and how the real estate side fits around the answers.
- Do you need the money from your current home to buy the next one
- Could you comfortably carry two homes for a while if a sale took longer
- Where would you stay, and where would your belongings go, between homes
- Are there tax or estate questions that a qualified advisor should review first
If the first answer is yes, selling first is usually the place to start. If the second answer is a comfortable yes, buying first becomes an option worth discussing. The third and fourth questions apply either way. Answering all four before you list or search turns a stressful decision into a clear plan, and it means you can explain your thinking to anyone helping you, including family members who may want to understand the reasons behind your choice.
Who answers which question
One of the most useful things you can do is send each question to the person qualified to answer it. Real estate questions belong with Linda. Financing belongs with a licensed lender. Tax and estate questions belong with a tax advisor or an estate or elder law attorney. Property questions go to a licensed home inspector, an insurance agent or Charlotte County. Here is a simple guide you can keep beside your notes.
| Question | Why it matters | Who to ask |
|---|---|---|
| Which order fits my sale and purchase | Sets the shape of the whole move | Linda, for the real estate side |
| What financing options might fit me | Decides whether buying first is realistic | A licensed lender |
| Are there tax effects from selling | Can change how you plan the sale | A tax advisor |
| Does the move affect my estate plans | Keeps documents and wishes up to date | An estate or elder law attorney |
| What will coverage cost on the new home | Affects the budget for either order | An insurance agent |
Notice that no single person answers everything. That is not a weakness in the process. It is how you protect yourself. When each question goes to the right source, you get clearer answers and fewer surprises. Linda can help you keep the questions organized and the real estate timeline moving, while the specialists handle the parts that belong to them. Bring their answers back together and the right order usually becomes obvious.
Planning for dates that do not match
Even with good planning, the closing of one home and the purchase of another rarely line up to the day. That is why a gap plan matters in either order. If you sell first, you may need a rental or a stay with family for a while. If you buy first, you may own both homes for a time. Decide in advance which arrangement you would choose, so a delay feels like a detour rather than an emergency.
It also helps to think about belongings separately from people. Furniture and boxes can go into storage while you stay somewhere smaller. Important papers, medications and everyday essentials should travel with you. Making a short list of what must stay within reach during the gap is a simple step that many people forget. A little preparation here makes the in between weeks feel organized instead of chaotic, wherever in Charlotte County you end up staying.
Your next step before a first conversation
Before you talk with anyone about the order of your move, gather a few things. You do not need final answers, only a clear picture of where you stand. Bring these notes to each conversation so the people helping you can see the whole plan, not just the piece they handle. Here is a short list to start with.
- A rough target move date and how flexible it really is
- Your questions for a lender about financing either order
- Any tax or estate questions to take to a qualified advisor
- Your preferred gap plan if the sale and purchase dates differ
When your notes are ready, bring them to Linda Swanson. Linda holds the Seniors Real Estate Specialist (SRES) designation, training focused on the questions that come up in later life moves, and will go through your plan one step at a time. There is no pressure to decide anything in that first conversation. The aim is simply to help you choose an order for your retirement move to Punta Gorda that fits your situation and your comfort.
This article is general information about moving, buying and selling homes in Punta Gorda and Charlotte County, Florida. It is not legal, tax, estate, lending, insurance or VA benefits advice and does not predict prices or promise results. Confirm zoning, flood and building questions with Charlotte County, financing with a licensed lender, VA loan and benefit questions with official VA resources, and tax, estate or care questions with a qualified advisor. Linda Swanson, Coldwell Banker Realty.
Written by